

Not Happy With Your Restoration Company? You Can Switch.
A lot of Michigan homeowners end up with whatever company their insurance company sent the night of the fire or flood. If you don’t like how the job is going, at the start, in the middle of drying or right before the rebuild, you can usually change contractors. Here’s how to do it without losing your records or paying for work that was never done.
Family-owned since 1993 • IICRC Certified Firm • Xactimate certified estimatorsWhy People Change Restoration Companies in the Middle of a Job
Most of the takeover calls we get start the same way. The insurance company brought in its own preferred vendor, and the homeowner didn’t like the way that company was running the job.
- Nobody explains what’s happening or what comes next
- Crews show up late, or not at all
- Fans and dehumidifiers were set up, but nobody checks the moisture readings
- The bill doesn’t match the work you saw done
- You feel pushed to sign for the rebuild before you’re ready
- You just don’t trust them in your home
The Company Your Insurer Sent Isn’t Your Only Choice
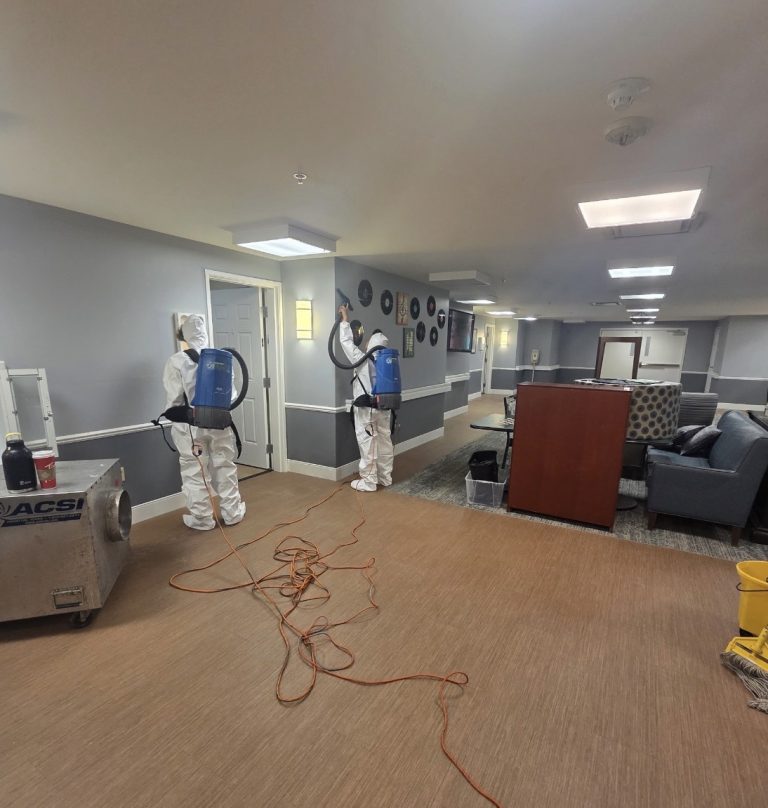
Insurance companies often send a contractor from their own list the first night. That can be a big help in an emergency. It doesn’t mean you have to keep them for the whole job.
How to Switch Without Losing Ground
Why the First Company’s Photos Matter So Much
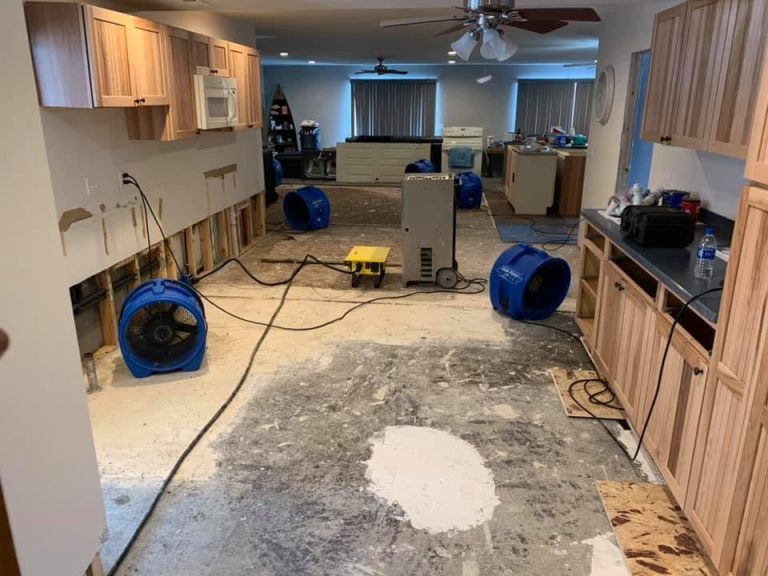
By the time we get the call, the drywall, flooring, trim and cabinets are often already torn out and hauled away.
The first company’s pre-demo photos are the only record of what was there: the type of flooring, the cabinet style, the trim and the finishes. They’re how we, and your adjuster, know what goes back in so you get your home back the way it was. The drying logs matter too. They show the framing and subfloor were dried to standard before anything gets closed up again.
If those records are missing, we rebuild the history from whatever we can find, but some details can be lost for good. The sooner you ask for them, the better.
Don’t Pay for Work That Wasn’t Done
One of the most common problems we see after a switch is a first-company invoice that doesn’t match the job, often when that company knows it won’t be doing the rebuild. Here’s what to check.
You owe a fair price for work that was actually done under your agreement. If the bill doesn’t look right, ask for an itemized invoice with the photos and logs behind it. For a dispute over the contract itself, talk to an attorney.
What Happens When Select Restoration Takes Over
Takeovers are a big part of what we do. Sometimes we pick up right where the last company stopped. Sometimes the records are a mess and we start from the ground up. Either way, here’s how it goes.
What we do
- Review the first company’s estimate and invoice and show you what doesn’t match the photos and logs
- Pick up the job with our own photos, readings and Xactimate estimate
- Handle the cleanup, the rebuild and your mortgage company’s draw inspections
What we don’t do
- Negotiate your claim or represent you with your insurance company. Michigan law doesn’t allow contractors to do that
- Give legal advice about your contract with the first company
- Pressure you to switch. It’s your home and your decision
Not Happy With How Your Job Is Going? Let’s Talk.
Free walkthrough and second opinion anywhere in Macomb, Oakland and Wayne County. We answer 24/7.
Frequently Asked Questions
Can I fire the restoration company my insurance company sent?
Usually, yes. Most homeowners policies leave the choice of contractor to you. Check your policy for “managed repair” wording, and read the work authorization you signed to see how the job can end.
Do I have to pay the first company?
Generally, you owe a fair price for work actually done under your agreement. Ask for an itemized invoice backed by photos and drying logs, and have it reviewed before you pay. For a contract dispute, talk to an attorney.
Will my insurance still pay if I switch contractors?
Switching contractors doesn’t cancel your claim. Your insurance company still pays for covered damage under your policy. The new contractor documents the remaining work and writes its own estimate. Keep your adjuster informed.
Can I switch after the demo is already done?
Yes. Many of our takeovers start after tear-out. That’s why the first company’s pre-demo photos and drying logs matter so much: they show what was there and prove the house was dried.
How do I get my photos and records from the first company?
Ask in writing for every photo, moisture reading, drying log, estimate and invoice for your property. Keep a copy of your request and everything you receive.
Does Select Restoration negotiate with my insurance company?
No. We’re a restoration contractor, not a public adjuster. We document the damage, write estimates, meet your adjuster and do the repairs. For help with a claim dispute, talk to a licensed public adjuster or an attorney, or contact Michigan DIFS at 877-999-6442.
More reading: Can I choose my own contractor on an insurance claim? · Free second opinions · $500 Upgrade Credit. This page is general information, not legal or insurance advice. Every contract and policy is different.
